Treasury Hits Bank of America With About $1.21 Billion in Penalties in Coordinated OFAC, FinCEN and OCC Actions
The U.S. Department of the Treasury announced on October 13 that the Office of Foreign Assets Control (OFAC), the Financial Crimes Enforcement Network (FinCEN) and the Office of the Comptroller of the Currency (OCC) have taken coordinated enforcement actions against Bank of America, N.A., totaling approximately $1.21 billion in penalties. Treasury said the package is the third-largest penalty in the department's history; the OCC's $750 million civil penalty is the largest in that agency's history, and the FinCEN penalty is the third-largest in FinCEN's history.
By component, FinCEN assessed a $1.2 billion penalty, of which $750 million is credited toward the OCC penalty, with the remaining $450 million payable by the bank to the Treasury; OFAC separately settled with the bank for $11,662,930 (about $11.66 million). FinCEN found that the bank willfully violated the Bank Secrecy Act: from at least January 1, 2018 through July 1, 2025, it failed to implement and maintain an effective anti-money laundering program, failed to conduct required due diligence on foreign correspondent accounts, and filed suspicious activity reports (SARs) late or not at all.
Treasury said the bank failed to timely report more than $5 billion in suspicious transactions, including more than $1 billion involving national-security and other priority illicit finance risks, including Chinese money laundering networks, fraud and trade-based money laundering linked to the southwest border; regulators also found the bank failed to adequately investigate trillions of dollars in potentially suspicious transactions despite knowing of significant compliance deficiencies. The OCC said the bank had failed to adequately fix the shortcomings identified under a 2024 cease-and-desist order.
The OFAC settlement resolves 475 apparent violations tied to transactions between September 18, 2021 and April 24, 2025, with a total value of about $14.8 million, spanning multiple sanctions programs including those on Iran, Russia, narcotics and global terrorism. According to Treasury, the breakdowns included payments involving blocked banks, sanctions alerts that were wrongly prioritized, delayed updates to sanctions watchlists and human error in handling blocked accounts; OFAC described the apparent violations as non-egregious but largely not voluntarily self-disclosed.
“When a bank of this size fails to meet its anti-money laundering and sanctions obligations, the consequences extend far beyond its own walls, exposing the entire U.S. financial system to significant illicit finance risks,” Treasury Secretary Scott Bessent said in a statement, adding that financial institutions are on the front lines of protecting U.S. economic and national security, and that the actions send a clear message that even the biggest financial institutions are not above the law.
Treasury said FinCEN's order also requires remediation, including third-party lookbacks to identify suspicious activity that may have been missed. A Bank of America spokesperson said the bank has dedicated substantial personnel and resources to its remediation efforts and that those costs are in its current expense base; the bank said its third-quarter results, due Wednesday, will include a $1.2 billion non-tax-deductible charge reducing quarterly net income by approximately 17 cents per share. Financial media reported the bank's shares fell about 2% in after-hours trading on Tuesday following the announcement.
(Source: U.S. Department of the Treasury press release, October 13, 2026; the bank's response and share move as reported by Reuters and Barron's)
Published by GSM · USA (original Chinese edition)
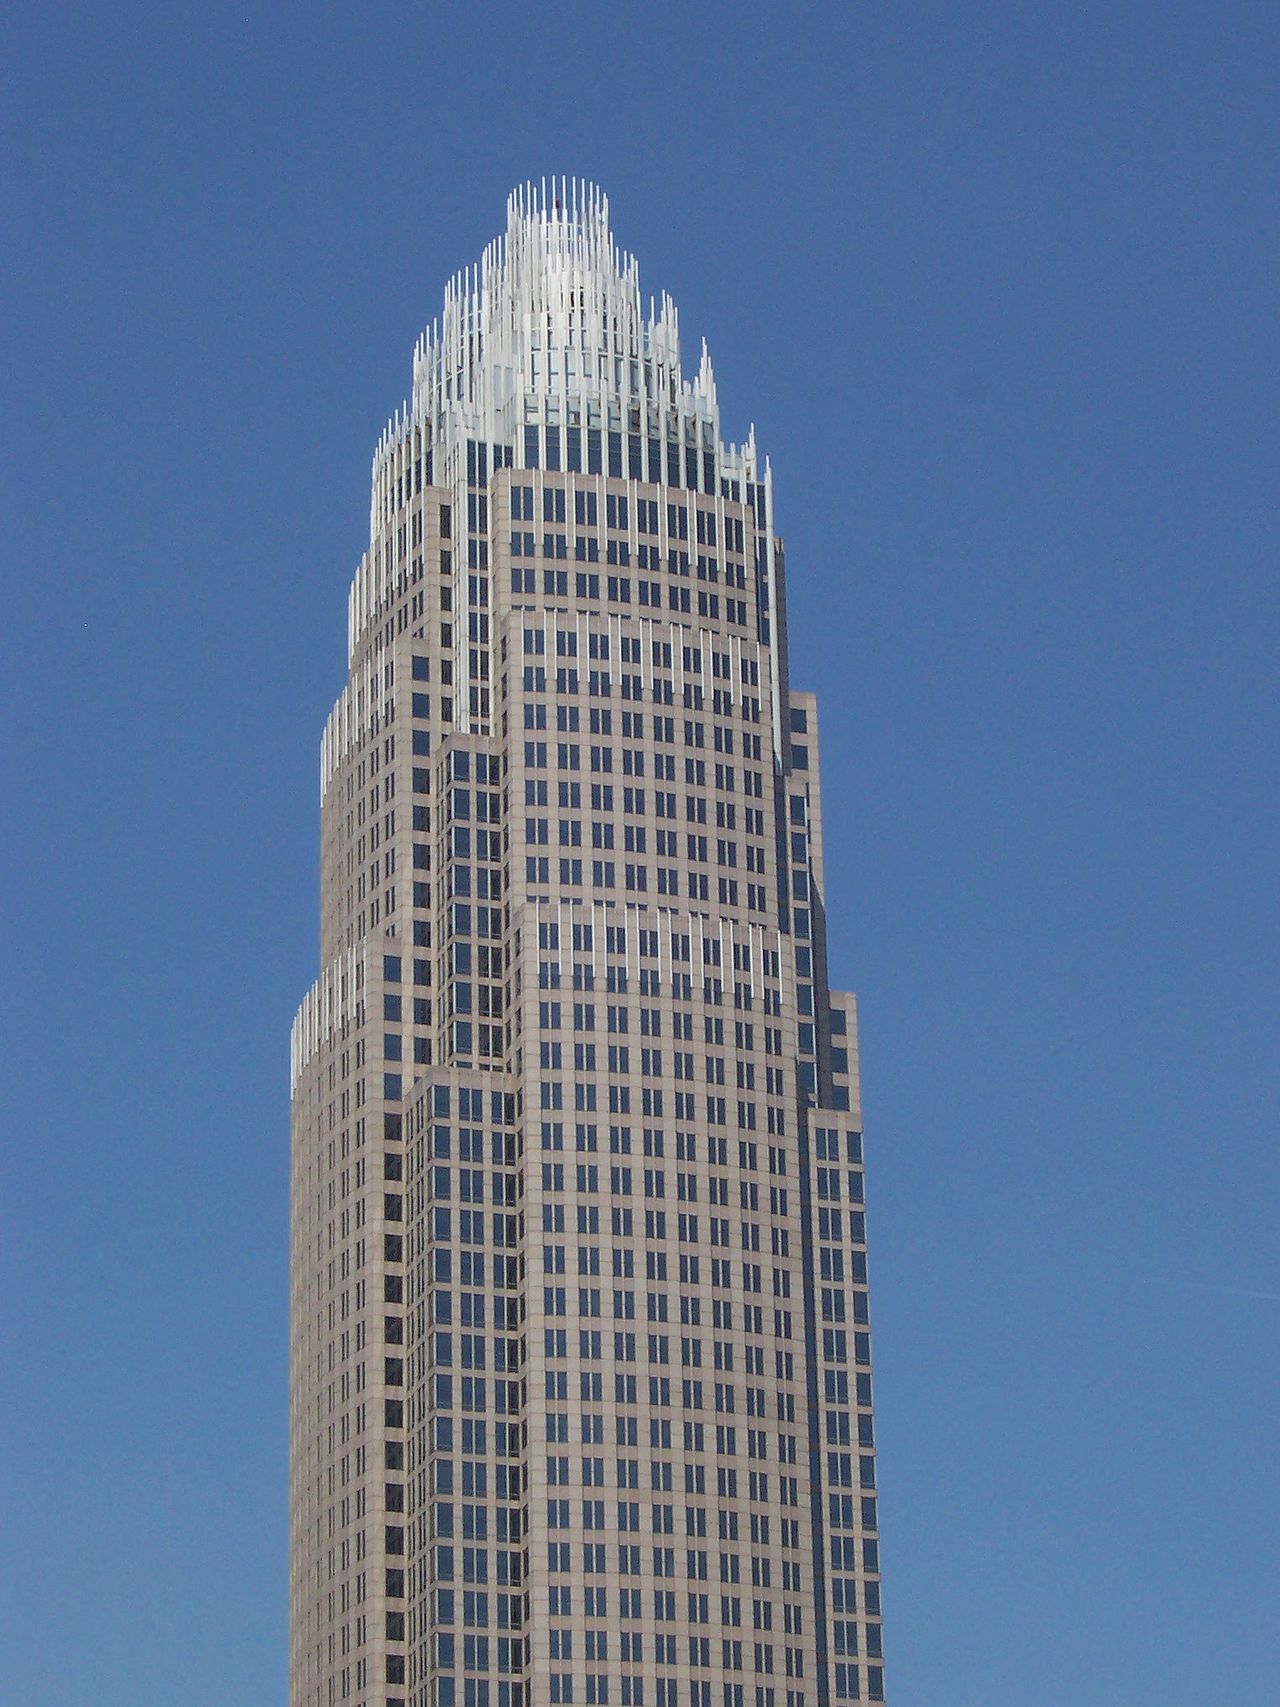
Photo: 美国银行总部大楼(北卡罗来纳州夏洛特),Wikimedia Commons,公有领域