Georgia Insurance Commissioner-Elect Waites Unveils First-100-Days Plan to Ban Credit Scores and ZIP Codes in Insurance Pricing
ATLANTA — Georgia Insurance and Safety Fire Commissioner-elect Keisha Sean Waites laid out her first-100-days plan in a post-election interview with WSB-TV (Channel 2 Action News) in Atlanta, Fulton County, Georgia, putting at the top a push for state lawmakers to ban insurers from using credit scores and ZIP codes to set premiums. "Those things have nothing to do with calculating your risk as it relates to your insurance premiums," she said.
Waites defeated Republican incumbent John King in the November 3 election by about 54% to 46%, with unofficial returns at 54.28% to 45.72%. Of the four states that elected insurance commissioners this year, Georgia was the only one to change party. She takes office in January 2027. Waites is a former state legislator and Atlanta City Council member who also worked at the Federal Emergency Management Agency (FEMA). King was appointed in 2019 by Governor Brian Kemp to finish the term of a predecessor convicted of fraud and embezzlement, and won a full term in 2022.
Her plan has three first-100-days priorities: asking lawmakers to ban credit scores and ZIP codes in insurance pricing; strengthening consumers' ability to take action and recover money when insurers are accused of wrongdoing or negligence; and streamlining Georgia's regulatory process to attract more insurers and increase competition. She has also pledged to speed up claims payments, hold insurers accountable for rates, and effectively freeze some auto and homeowners insurance rates. On rates themselves, she said a commissioner cannot simply freeze them, but the office can scrutinize proposed increases and delay or deny them when insurers do not provide actuarial data supporting the higher prices.
The effect of credit on Georgia premiums is measurable. A MoneyGeek analysis found that a Georgia driver with poor credit pays $3,139 a year for full coverage, $1,839 more than the same driver with excellent credit, or about $153 a month; the excellent-credit driver's premium is about $1,300 a year. ZIP codes move premiums less across most of the state: the middle 80% of ZIP codes span a $761 range, from the most expensive, 30311 in southwest Atlanta at $3,483 a year, to the least expensive, 31605 in Valdosta at $1,247.
Whether the ban happens is up to the General Assembly. Then-state Senator Nabilah Islam Parkes filed three bills along the same lines in February 2026: SB 505 would require the commissioner to approve auto and homeowners rates before insurers use them, SB 506 would bar geographic classifications including ZIP codes in auto pricing, and SB 507 would prohibit the use of credit information and credit scores in underwriting and rating. All three were referred to committee on February 17, none received a vote, and all died when the 2025-2026 session ended; any version would have to be filed again when the new General Assembly meets in January. According to Experian, four states — California, Hawaii, Massachusetts and Michigan — bar auto insurers from using credit in pricing, and Georgia would be the fifth if a ban passed. Analysts note a ban would shift costs among drivers rather than lower the total, since insurers would still price expected claims through the rating factors that remain.
(Source: WSB-TV)
Source: WSB-TV
Published by GSM · USA (original Chinese edition)
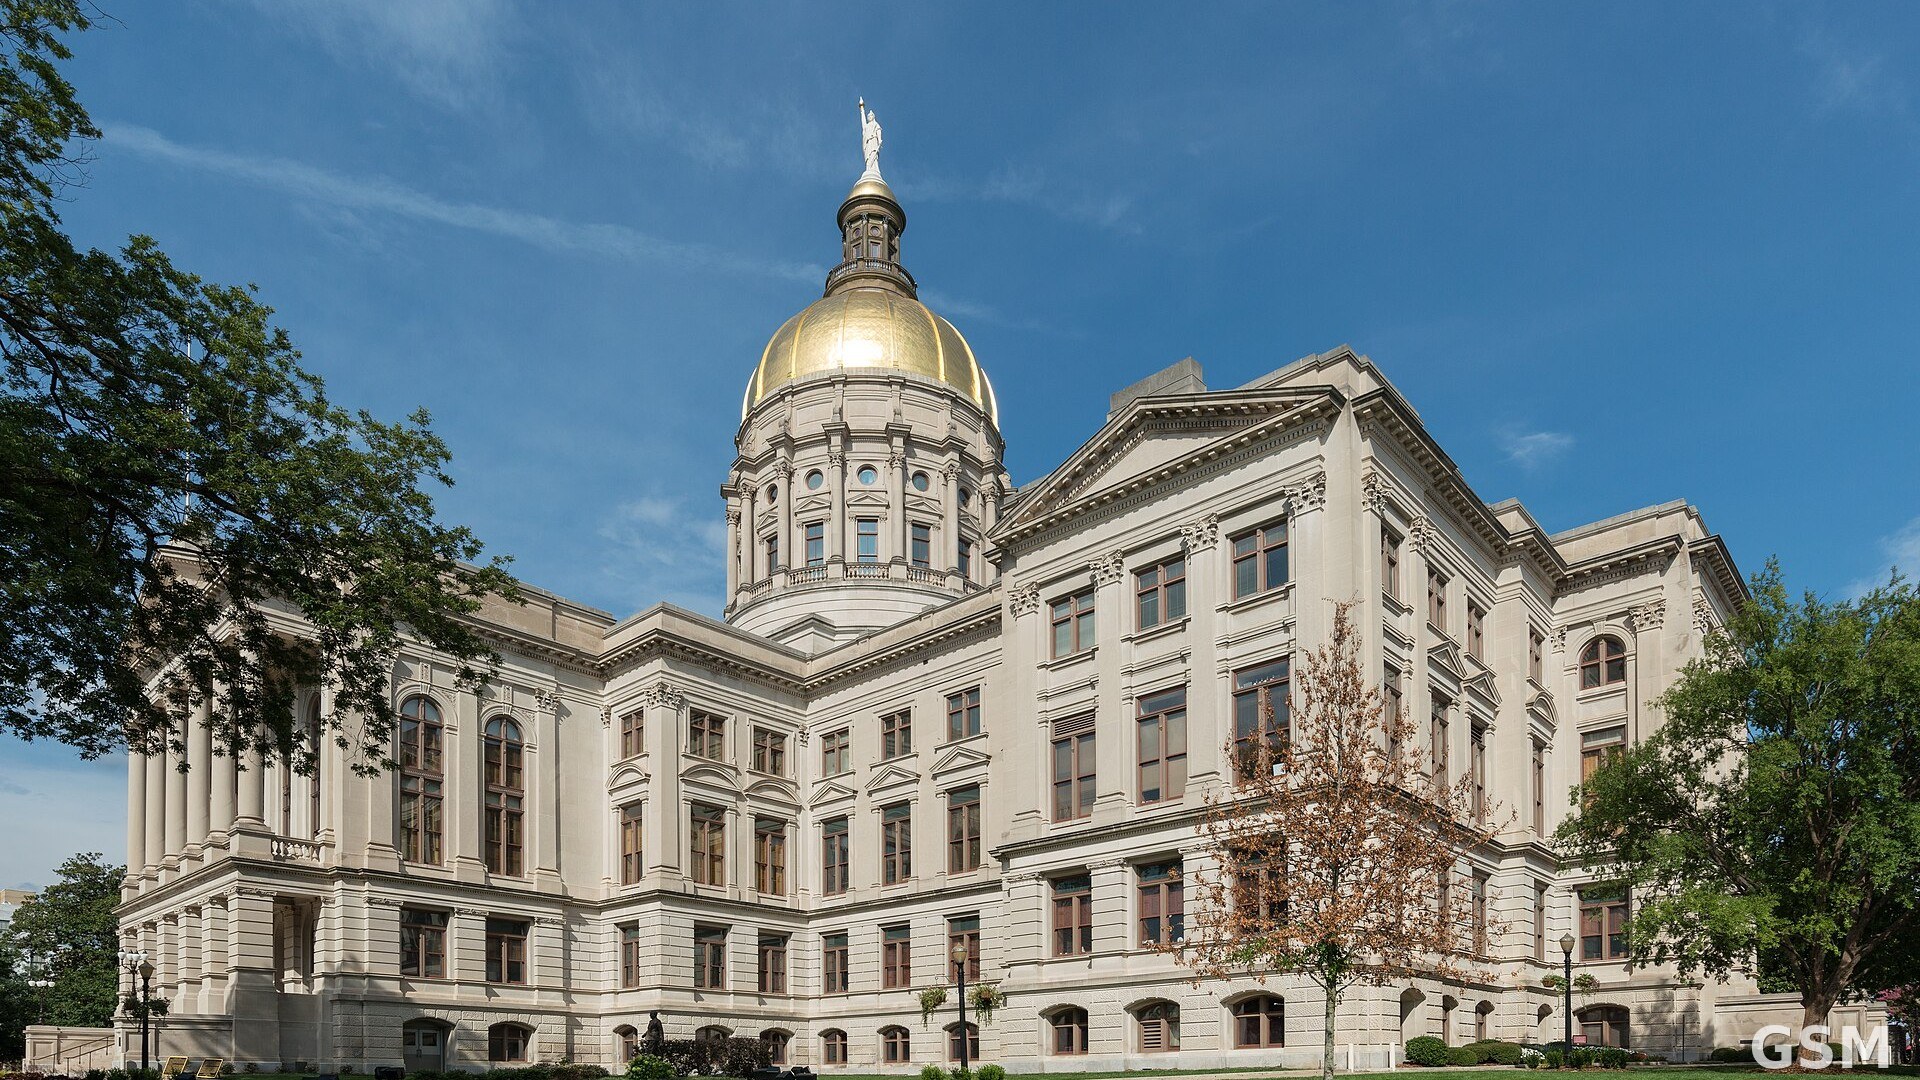
Photo: 图:位于 Atlanta 的佐治亚州议会大厦西面,金色圆顶是该州地标。DXR 摄,CC BY-SA 4.0,经 Wikimedia Commons。 / Photo: West view of the Georgia State Capitol in Atlanta, with its gold dome. Photo by DXR, CC BY-SA 4.0, via Wikimedia Commons.