SEC Proposes Executive and Director Compensation Disclosure Reforms: Named Executives Would Shrink From Five or More to Two
The U.S. Securities and Exchange Commission (SEC) on November 13 in Washington proposed rule amendments to make its executive and director compensation disclosure requirements more principles-based and materiality-driven, providing investors with clearer, more concise, and less complex disclosures. The requirements were last comprehensively reformed in 2006, and the proposal follows a request for public comment and a roundtable with representatives from public companies, investors, and other experts.
Under the proposal, the named executive officers whose pay must be disclosed would encompass the principal executive officer and the principal financial officer, the positions whose compensation is generally most material for investors, reducing the number from typically five or more individuals under the current rule to two in most circumstances. The primary tabular disclosure would be rebuilt into three new tables, an Earned Compensation Table, a Granted Compensation Table, and a Status of Equity Awards Table, replacing the four primary tables now required and improving investors' ability to track equity awards through their lifecycle.
The proposal would raise the minimum aggregate reporting threshold for perquisites from $10,000 to $150,000 and introduce a new de minimis tracking exclusion. The Compensation Discussion and Analysis would become more principles-based, requiring registrants to address only three topics and eliminating the list of 15 example topics in the current rule. Pay-versus-performance disclosure would be simplified by reducing the required performance measures and replacing the complex "Compensation Actually Paid" calculation with the total compensation earned amount from the proposed Earned Compensation Table.
Under the pay ratio rule, the population used to determine the median employee would be limited to U.S. full-time employees, and the determination would be required only every five years. The proposal would also eliminate required check boxes from annual report cover pages and certain potentially redundant disclosures about clawback policies, while leaving the underlying clawback mechanics unchanged.
SEC Chairman Paul S. Atkins said the amendments reflect a comprehensive reform of Item 402 of Regulation S-K and aim to elicit more informative disclosure rooted in materiality. The Commission said the changes aim to reduce compliance burdens where there is not commensurate benefit for investors. The public comment period will remain open for 60 days following publication of the proposing release in the Federal Register.
(Source: U.S. Securities and Exchange Commission)
Source: U.S. Securities and Exchange Commission
Published by GSM · USA (original Chinese edition)
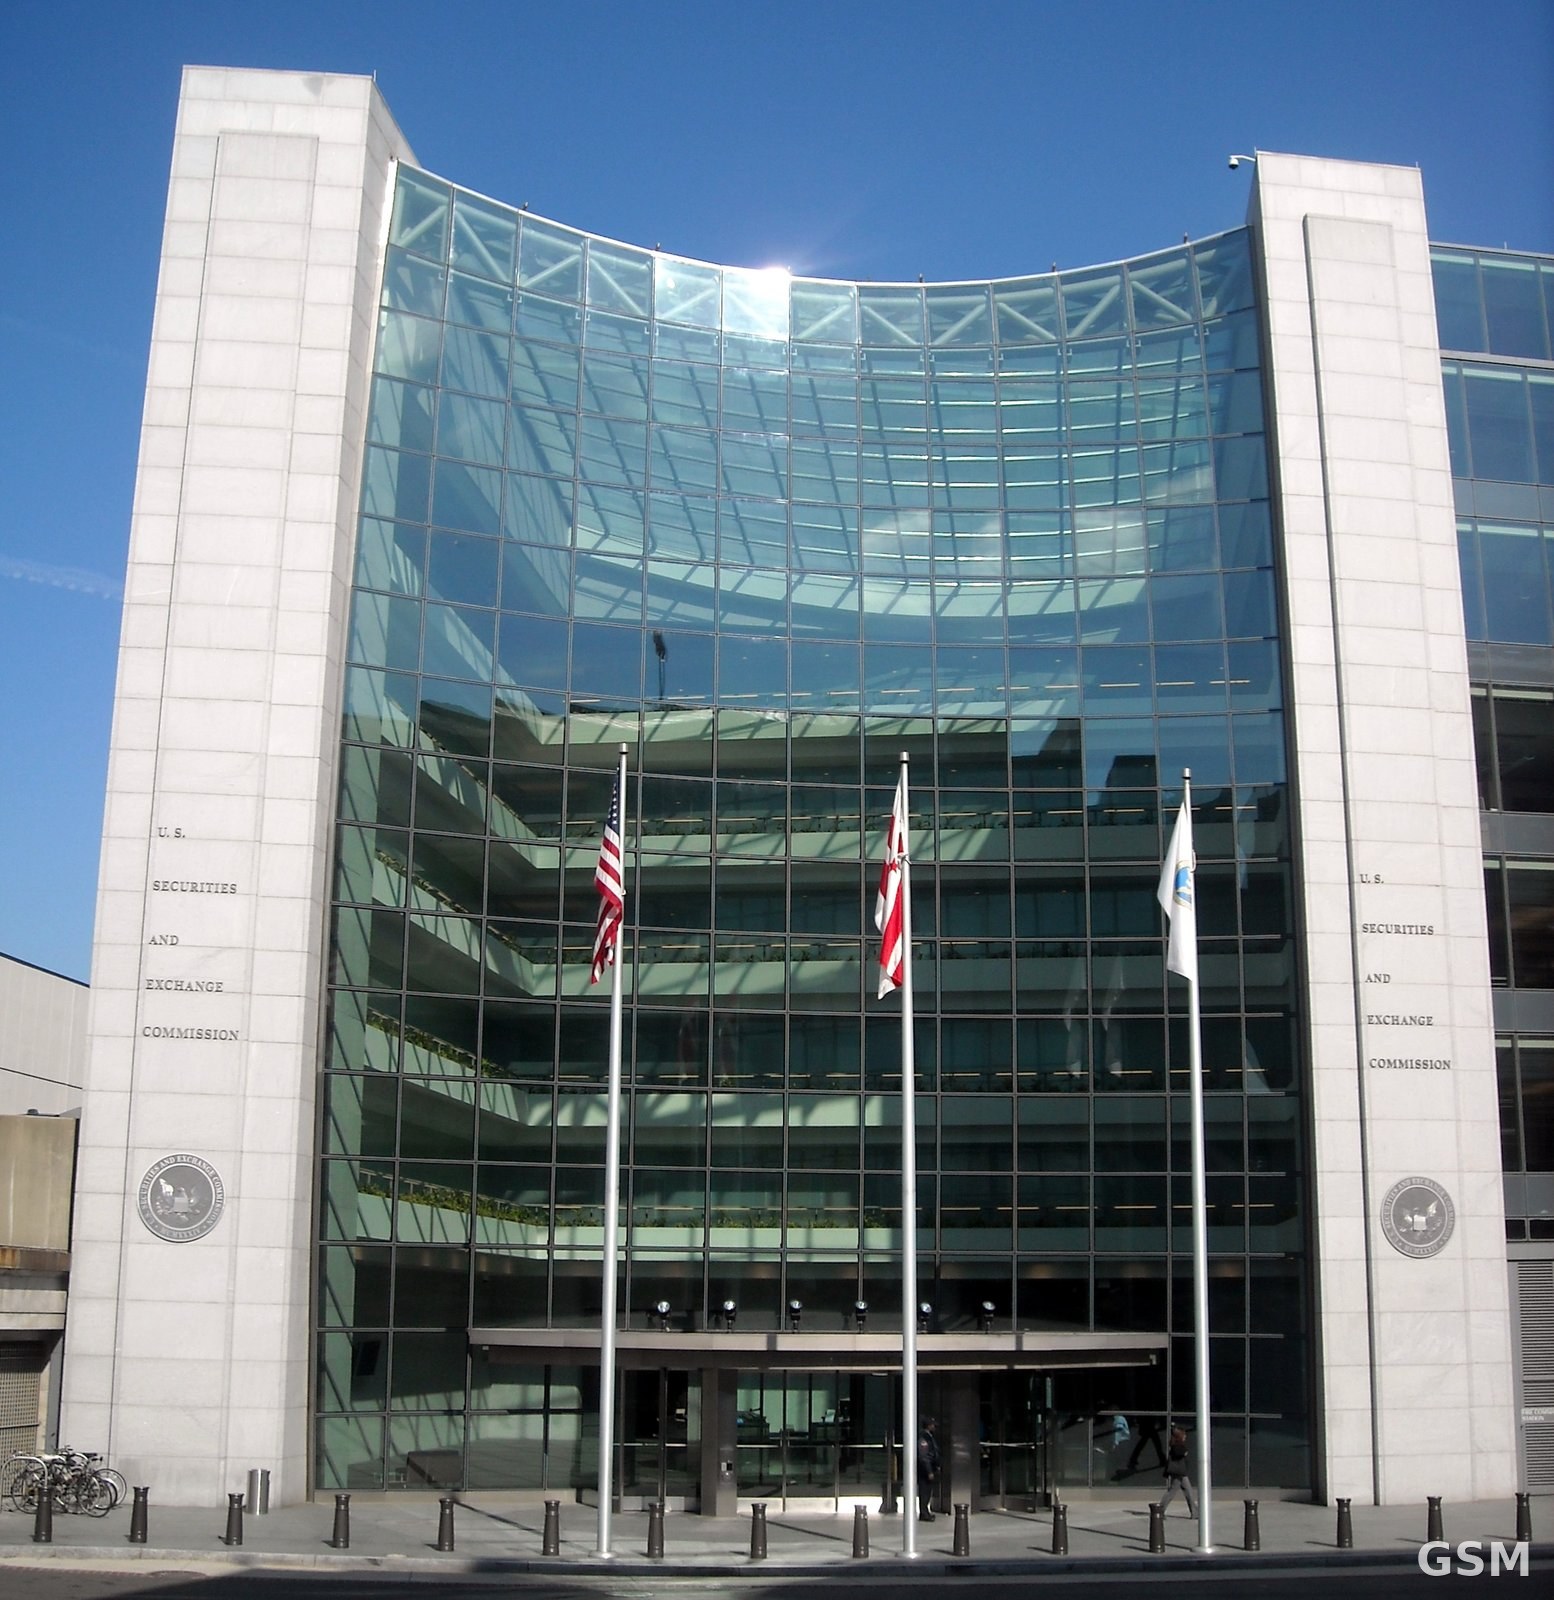
Photo: 图:位于华盛顿的美国证券交易委员会(SEC)总部大楼。GSM联邦核心固定图库。 / Photo: The headquarters of the U.S. Securities and Exchange Commission in Washington. GSM federal core asset library.